Optical Inventory Financing for Optometry Practices
Optical inventory financing helps optometry practices fund frames, contact lenses and related stock without draining the cash they need for payroll, rent and daily operations. For many practices, the optical is a meaningful source of revenue, but keeping a well-stocked frame board means paying for product long before patients buy it.
This guide explains why inventory ties up cash, which financing tools practices tend to consider and how to use them carefully. Tax treatment of inventory and financing costs varies, and nothing here is legal, tax or accounting advice. An accountant can help with inventory accounting questions.
Why Optical Inventory Strains Cash Flow
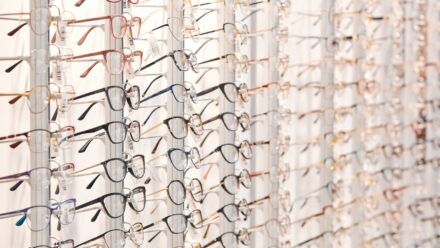
Unlike exam fees, optical sales depend on having the right product on display. A patient who cannot find a frame they like may take their prescription elsewhere. That pressure leads many practices to carry a broad selection, and the cost adds up.
Several factors make the cash squeeze worse:
- Upfront purchasing: frames are often bought well before they sell, and some vendors require minimum orders
- Slow-moving styles: frames that do not sell tie up cash and may need to be marked down or returned
- Seasonal patterns: back-to-school and year-end benefit cycles can create spikes in demand
- Vision plan timing: optical sales paid through vision plans may be reimbursed later than a cash sale
- Contact lens stock: trial lenses and annual supplies add another layer of inventory
When all of this hits at once, even a profitable practice can find itself short on cash.
When Optical Inventory Financing Makes Sense
Financing inventory can be reasonable when it supports sales that the practice can reasonably expect to make. Typical situations include:
- Refreshing a tired frame board after years of underinvestment
- Adding a premium or specialty frame line to attract new patients
- Stocking a new optical after a build-out or relocation
- Preparing for seasonal demand without squeezing payroll
- Buying a practice whose optical needs to be restocked after closing
Financing is generally less helpful when inventory is not turning. If frames are sitting on the board for a long time, borrowing to buy more may only deepen the problem. Reviewing sell-through by brand, style and price tier before borrowing is a sensible first step.
Common Ways Practices Finance Optical Inventory
Most optical inventory financing falls under the broader category of working capital. Options may include:
Revolving line of credit: A line of credit lets the practice draw funds when it needs to buy inventory and repay as sales come in. Interest is typically charged only on the amount drawn. Our guide to the optometry practice line of credit explains how these lines generally work.
Working capital term loans: A term loan provides a lump sum that is repaid over a set schedule. This can fit a one-time project, such as restocking an entire optical, better than a revolving line.
Vendor terms: Some frame and lens suppliers offer extended payment terms, consignment or return privileges. These arrangements vary and should be read carefully, but they can reduce how much the practice needs to borrow.
Including inventory in an acquisition loan: When buying a practice, inventory and post-closing working capital may sometimes be included in the overall financing, depending on the lender and program rules.
Eligibility and terms for any of these depend on the business, the borrower, the use of proceeds, program rules and lender review. Every loan is subject to approval, and nothing here is a commitment to lend.
How Lenders View Optical Inventory
Lenders tend to look at inventory through the lens of cash flow rather than as stand-alone collateral. Frames lose value as styles change, so most lenders focus on the practice’s overall ability to repay.
They may review:
- Historical revenue split between professional services and optical sales
- Cost of goods sold and gross margin on optical
- How quickly inventory turns over
- Reliance on vision plans and how they reimburse materials
- Existing debt and how a new obligation fits with it
Practices that rely heavily on vision plans may see thinner optical margins. Our article on vision plan dependence and optometry practice loans covers how lenders and buyers view that issue.
Managing Inventory So Financing Works Harder
Optical inventory financing works best alongside disciplined inventory management. Practices often benefit from:
- Tracking sell-through by frame line and price point
- Setting a target inventory level and sticking to it
- Returning or rotating slow-moving frames where vendor terms allow
- Training opticians to present options across price tiers
- Reviewing cost of goods regularly with an accountant
Better turns can reduce how much the practice needs to borrow and lower the overall cost of carrying stock. For more ideas, see our article on ways to increase practice cash flow without new debt. Our guide to optometry practice overhead also explains how cost of goods affects overall profitability.
Questions to Ask Before You Borrow
- Will this inventory sell within a reasonable period based on past patterns?
- Does the repayment schedule match when optical revenue is collected?
- Is a revolving line or a term loan a better fit for this purchase?
- Are vendor terms available that would reduce borrowing?
- How will the payment affect cash flow during slower months?
Final Thoughts
Optical inventory financing can help an optometry practice keep a strong frame selection without starving the rest of the business of cash. Used thoughtfully, and paired with good inventory management, it can support optical sales while preserving the reserves a practice needs for payroll and growth.
US Medical Funding helps optometrists access working capital for inventory, payroll and day-to-day needs. Learn more about our optometry practice working capital financing and our broader working capital solutions.